Time-of-Day Decay Analysis
By the time the first candle closes after the cash open, the initial momentum is already fading. The decay in success occurs as the day moves forward, as the notes at orb trading win rate braunmedicalmedia describe. This data shows a clear drop in the orb win rate during the middle of the session.
The Mechanics of Momentum Decay
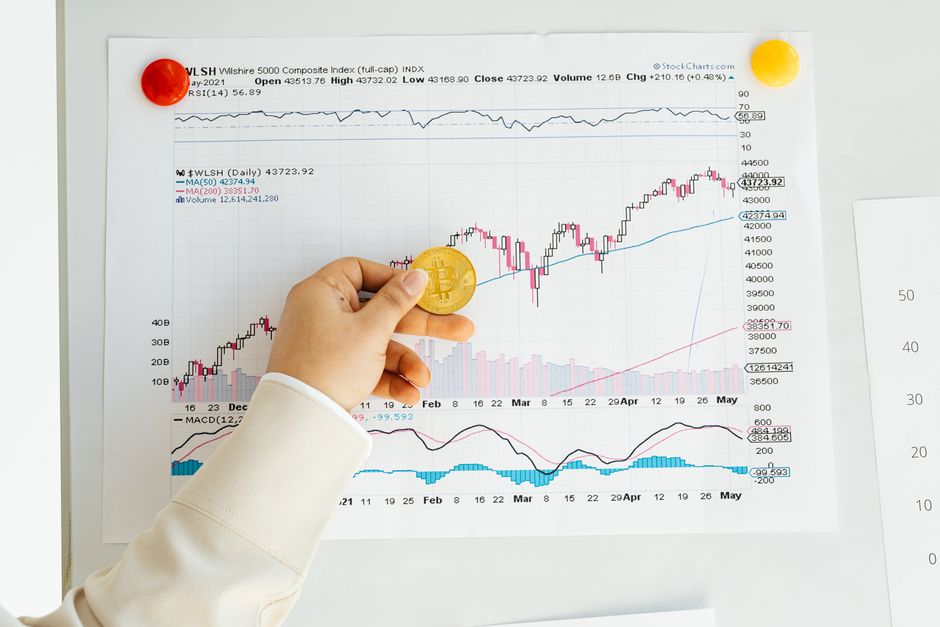
Volatility is highest during the first fifteen minutes of regular trading hours. A breakout from the five minute range often carries significant weight because the volume is concentrated. As the clock moves toward midday, the liquidity shifts. The edge found in an opening range breakout tends to evaporate as the market enters a period of consolidation. A trade taken at 10:30 AM lacks the velocity present at 9:35 AM. The data confirms that the probability of a sustained move decreases the further the price travels from the opening bell.
Timeframe Sensitivity and Volume
A 15 minute timeframe provides a different signal than a 5 minute setup. During the first hour, the price action respects the boundaries of the opening range with high frequency. Once the market passes the midmorning mark, the price often oscillates within a tighter channel. This lack of directional conviction makes the signal less effective. The volume profiles show that the aggressive participants have largely completed their primary moves before the lunch hour begins. Executing a trade during this lull often results in being caught in chop.
Measuring the Decay Curve
The decay is not linear. It follows a specific curve that starts after the initial burst of activity. An opening range breakout works with higher frequency when the range is established within the first thirty minute range. As the session progresses, the tendency for mean reversion increases. The intraday trend often stalls once the morning volatility is spent. A signal that triggers at 11:00 AM has a lower mathematical expectation than one triggered at 9:45 AM. The data reflects a steady decline in the win rate as the midday period approaches.
Comparing Morning and Midday Profiles
The difference between the early morning and the midday period is stark. In the early stages, the session high is often set during the first hour. By the time the midday lull hits, the market often moves sideways. Using a 60 minute range to define the boundaries provides more stability, but it also catches more of the decay. The most profitable moves are concentrated in the period immediately following the market open. Later signals require much higher volume to overcome the lack of natural momentum.
Statistical Observations
A small sample overstates the edge. Large datasets show that the effectiveness of the signal is highly dependent on the time of day. The decay is a physical reality of how order flow is distributed. The concentration of orders at the start of the day creates the breakout potential. As the day matures, the orders become more balanced, leading to the observed drop in success. The math remains consistent across different equity sectors.